


Invisalign’s Moment of Truth: Will International Growth Save ALGN on Oct 28?
Invisalign’s Moment of Truth: Will International Growth Save ALGN on Oct 28?
Rich DupreySun, October 25, 2026 at 3:51 PM UTC
0
RORONOR / Shutterstock.com (RORONOR / Shutterstock.com)Quick Read -
ALGN ships a record 691.8K aligners in Q2, but scanner revenue drops 10.8% to $185.3M as practices shift to cheaper options.
Four straight EPS beats haven't moved the stock. Shares fell 3.7% after Q2 and sit down roughly 11% from the post-earnings close.
ASP is set to fall sequentially from $1,260 due to geographic mix, FX, and lower-priced products, putting pressure on international volume to compensate.
Building a portfolio and living off one are two completely different skills, and almost nobody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Align Technology (NASDAQ:ALGN) reports third-quarter results on October 28. North America is flat and scanner revenue is shrinking, so I'll be watching whether double-digit international aligner growth can keep the Invisalign story moving.
Record Aligner Volumes Meet Shrinking Scanner Sales
In Q2, Align shipped a record 691.8K Clear Aligner cases, +7.4% YoY. Revenue reached $1.056B (+4.3% YoY), and non-GAAP EPS of $2.64 topped the $2.60 consensus. APAC, EMEA and Latin America all posted double-digit volume growth, while North America held steady.
Imaging Systems and CAD/CAM Services was the weak spot. Revenue there fell 10.8% to $185.3M as practices moved to cheaper scanners, leases and rentals.
Since then, talks with Elliott Management produced three new independent directors, a strategic and operating model review and a larger 2026 buyback of $400M to $500M. Shares closed at $173.41 after the Q2 report and now sit at $154.51, down 1.05% year to date.
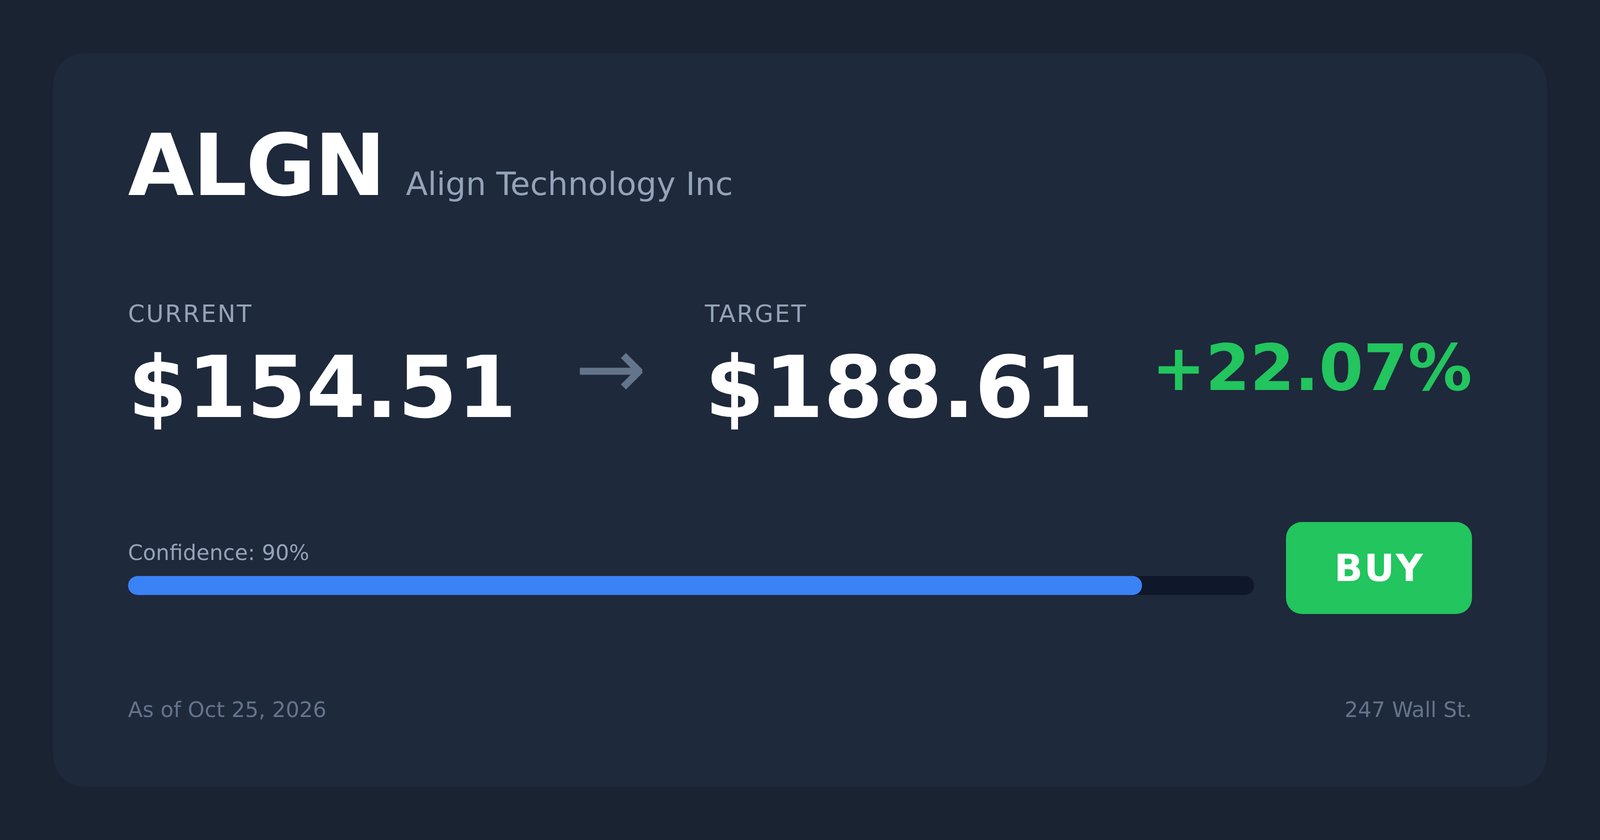
ALGN Price Target — 24/7 Wall St.Wall Street Expects Modest Q3 Growth
Metric
Consensus
Prior Year
Implied YoY Growth
Q3 Normalized EPS
$2.7655
$2.61
+6.0%
Q3 Revenue
$1.004B
$995.7M
+0.9%
FY 2026 EPS
$11.2073
$10.51
+6.6%
FY 2026 Revenue
$4.150B
$4.035B
+2.8%
The Q3 EPS estimate has slipped from $2.8979 90 days ago, with one downward revision in the past month and none up.
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer. It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›
Advertisement
International Volume Must Outrun Pricing Pressure
Management guided Q3 aligner volume up mid-single digits YoY, so overseas markets must keep doing the heavy lifting. CEO Joe Hogan sounded confident in July: "With that kind of a mix, it gives me a lot of confidence... because it's never the same all over the world."
That growth carries a cost. Management expects ASP to fall sequentially from $1,260 due to geographic mix, FX, China and Europe seasonality and lower-priced products like DSP. I'll be watching whether volume gains beat that drag. The UK also began charging 20% VAT on aligners on September 7, 2026, and management is monitoring volume effects.
North American retail demand among independent practices remains soft. Hogan called restoring consistent growth there "a top priority." Recent Wall Street downgrades highlighted soft domestic patient traffic, so you should look closely at regional commentary.
Scanner revenue is guided down 6% to 8% for 2026. John Morici framed the leasing shift as calculated: "We are giving up certain economics at the point of sale to expand patient access to treatment." Rising placements would support that case.
Margins round out the list. Align guided Q3 non-GAAP operating margin to about 24.0% despite $35M to $50M in one-time charges.
Four Straight Beats Have Failed to Lift Sentiment
Align has topped EPS and revenue estimates four straight quarters, yet shares fell 3.7% after Q2 and 1.34% after Q1. A Ninth Circuit ruling that revived antitrust claims adds another concern. The report must show international growth absorbing ASP and scanner pressure while margins advance toward the 23.7% full-year target. Clear evidence of that, plus concrete progress from the strategic review, would give the turnaround story real credibility.
Released: The Definitive Guide to Retirement Income
(Sponsor) Most people spend their entire working lives focusing on one thing: growing a pile of money. Then they retire and discover the skill they actually need is close to the opposite. Turning that pile into steady income, year after year, through good markets and bad, without ever running out.
It may be the least discussed and most consequential transition in personal finance, and plenty of otherwise careful investors walk into it with no real plan. That is exactly what The Definitive Guide to Retirement Income helps answer. It is a free guide from Fisher Investments covering what your retirement will really cost, where the cash flow should come from, and how much you can safely withdraw each year. Learn more here. Learn More Here ›
Contact editorial@247wallst.com for any questions or corrections.
Source: “AOL Money”
